50/30/20 Budget Rule: A Simple Guide for Beginners
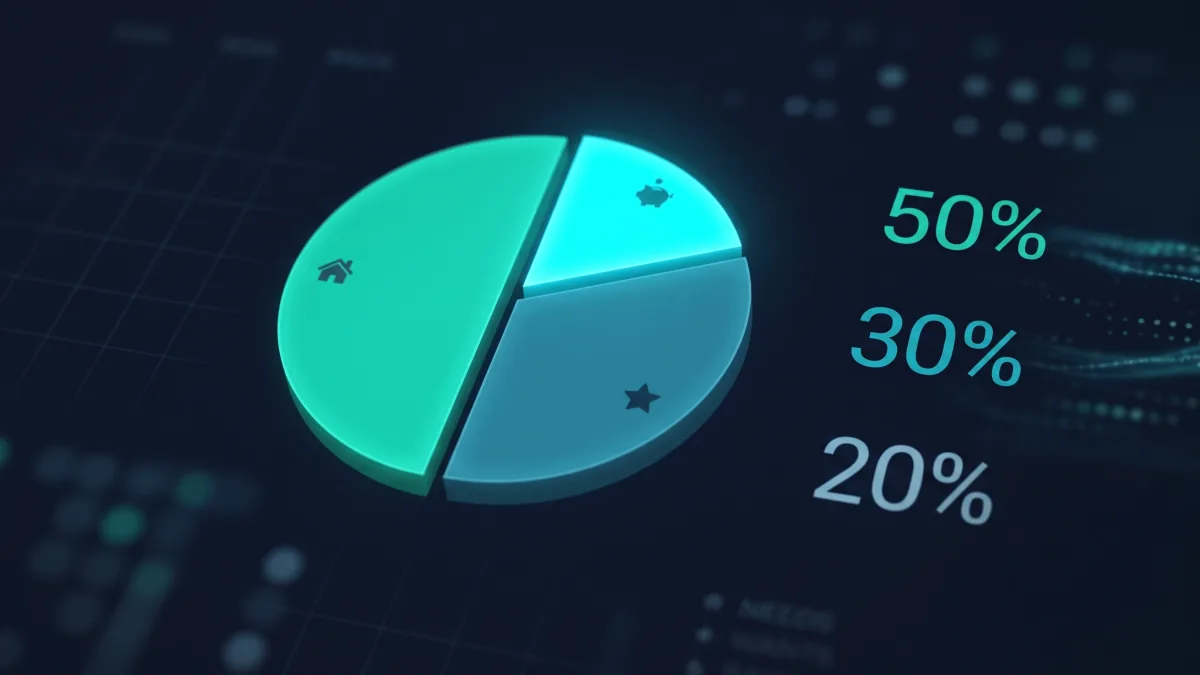
The 50/30/20 budget rule divides your take-home income into three groups: 50% for needs, 30% for wants, and 20% for savings and debt repayment. Treat it as a starting point, not a strict law.
On this page21
- What is the 50/30/20 budget rule?
- How do you calculate the 50/30/20 split?
- What counts as a need versus a want?
- How do you set up your 50/30/20 budget?
- What if the 50/30/20 rule does not fit?
- If housing and essential costs are high
- If your income changes from month to month
- If you are paying off debt
- If you cannot save 20% yet
- What are common budgeting mistakes?
- Quick-start checklist
- Frequently Asked Questions
- Is the 50/30/20 budget rule realistic?
- Is the 50/30/20 rule based on gross or net income?
- What should I do if my needs exceed 50%?
- Does the 20% category include debt repayment?
- What if I get paid weekly or every two weeks?
- Can I use the 50/30/20 rule with irregular income?
- Should I save 20% even if I have debt?
- What is the difference between the 50/30/20 rule and zero-based budgeting?
- Conclusion: What should you do first?
What is the 50/30/20 budget rule?
The 50/30/20 rule divides take-home income into three broad categories: 50% for needs, 30% for wants, and 20% for savings and debt goals. It offers beginners a quick way to organize money without tracking dozens of categories.
The U.S. Consumer Financial Protection Bureau (CFPB) describes a similar 50/20/30 rule of thumb and notes that people can create a personal spending rule that suits their circumstances. The percentages are a guideline, not a legal requirement or a guarantee that the same split works for every household.
Here is what the terms mean in this article:
The aim is not to judge every purchase; it is to make spending choices visible before the money is gone.
How do you calculate the 50/30/20 split?
Multiply your monthly take-home income by 0.50, 0.30, and 0.20 to calculate the suggested amounts for each category. The calculation is the same in dollars, pounds, euros, riyals, or any other currency; only the currency symbol changes.
Use take-home income: the money that reaches you after tax and payroll deductions. If you already have retirement contributions deducted before your pay arrives, do not count those same contributions a second time unless you deliberately add them back and use a consistent method.
| Monthly take-home | Needs: 50% | Wants: 30% | Savings & extra debt: 20% |
|---|---|---|---|
| CU 2,000 | CU 1,000 | CU 600 | CU 400 |
| CU 4,000 | CU 2,000 | CU 1,200 | CU 800 |
| CU 6,000 | CU 3,000 | CU 1,800 | CU 1,200 |
For example, if your take-home pay is CU 4,000 a month, the suggested needs limit is CU 2,000, your wants target is CU 1,200, and your savings and extra debt-repayment target is CU 800. Check: CU 2,000 + CU 1,200 + CU 800 = CU 4,000.
To try the calculation yourself: write down your monthly take-home income, multiply by 0.50 for needs, by 0.30 for wants, and by 0.20 for savings and extra debt repayment. Compare these targets with your actual bills. Do not change essential bills just to make the table look right.
What counts as a need versus a want?
A need supports basic living, health, safety, dependents, or work. A want is more flexible and can usually be reduced or delayed. Some expenses depend on circumstances: a car may be optional with reliable public transport but necessary when no practical alternative exists.
| Expense | Usually a need when… | Usually a want when… |
|---|---|---|
| Housing | Rent, mortgage, or basic utilities | Optional upgrades or extra space |
| Food | Groceries and basic meals | Takeout and restaurant meals you could reduce |
| Transport | Practical travel to work or essential appointments | Convenience rides or an unnecessary extra vehicle |
| Phone and internet | Basic service needed for work, study, or essential contact | Premium plans or optional subscriptions |
| Healthcare | Essential treatment, medicine, or required coverage | Optional services not needed for current health needs |
| Entertainment | Usually not essential | Streaming, games, events, hobbies, and leisure trips |
| Debt payments | Required minimum payments | Extra payments above the minimum — counted in the goals category |
Use the table as a guide, not a universal verdict. Ask: what happens if I reduce this? If health, safety, basic living, or income would be put at risk, it may belong in needs.
How do you set up your 50/30/20 budget?
Set up your budget by calculating take-home income, recording expenses, sorting them into the three categories, and planning for next month. A spreadsheet or notebook is enough.
- Calculate income. Add the pay you expect after deductions. For irregular pay, use a cautious estimate.
- List essentials. Include housing, utilities, groceries, essential transport, healthcare, childcare, insurance, and required minimum debt payments.
- Record flexible spending. Add dining out, entertainment, optional subscriptions, nonessential shopping, and other wants.
- Set goals. Choose amounts for emergency savings, planned future costs, longer-term goals, and extra debt payments above minimums.
- Calculate and compare. Multiply income by 50%, 30%, and 20%, then compare the targets with actual spending. If needs exceed 50%, adjust the split rather than skipping essential bills.
- Check timing and review. Match due dates to paydays, track spending through the month, and update the plan after comparing it with actual results.
What if the 50/30/20 rule does not fit?
Adjust the percentages when they do not match your cost of living, income stability, family needs, or debt obligations. A useful budget reflects reality.
If housing and essential costs are high
If rent, utilities, childcare, transport, or healthcare take more than half your take-home pay, the target may not fit. A 60/25/15 split is one illustration: 60% needs, 25% wants, 15% savings and extra debt repayment. It is not a universal recommendation; test the math against your bills. If essentials exceed income, cutting small treats may not be enough — review major fixed costs or seek reputable nonprofit financial counseling if available.
If your income changes from month to month
Use a cautious estimate rather than your best month. Keep some surplus from stronger months to cover weaker months and irregular bills.
If you are paying off debt
Include required minimum payments so they are not overlooked. In this method, extra payments go into the 20% category. If debt is a major burden, adjust the split; never miss required payments or essential expenses just to meet a savings target.
If you cannot save 20% yet
Start with an amount that does not put essentials or required bills at risk. If practical, set it aside on payday and review it as costs change. The CFPB emphasizes that a spending rule should fit the person using it.
What are common budgeting mistakes?
A budget is a living plan. If actual spending regularly differs from the target, update the figures.
Quick-start checklist
Frequently Asked Questions
Is the 50/30/20 budget rule realistic?
It can work when essential costs fit within roughly half of take-home income and there is room for wants and future goals. If rent, childcare, healthcare, or required debt payments take a larger share, adjust the percentages. It is a starting framework, not a pass-or-fail test.
Is the 50/30/20 rule based on gross or net income?
It is generally calculated from take-home income: money available after taxes and payroll deductions. Use a consistent method for automatic retirement or savings contributions so the same money is not counted twice. If pay varies, estimate cautiously and review often.
What should I do if my needs exceed 50%?
Check that your totals reflect genuine essential expenses and current bills. Do not skip required payments to satisfy a target. You can assign a larger percentage to needs, reduce wants, and review whether major fixed costs can realistically change.
Does the 20% category include debt repayment?
In this guide, the 20% category includes savings and extra debt payments above required minimums. Minimum payments are counted with needs to make essential monthly obligations visible. Other budget frameworks classify debt differently, so choose a clear method and apply it consistently.
What if I get paid weekly or every two weeks?
Convert expected take-home pay to a monthly planning amount or apply the percentages to each paycheck. Align bill due dates with when the money arrives.
Can I use the 50/30/20 rule with irregular income?
Yes, but use a cautious estimate and plan for lower-income months. Keep a buffer for months when income falls below your estimate.
Should I save 20% even if I have debt?
The rule does not require one universal answer for every debt situation. Include required payments in your budget first, then consider how to divide the remaining goals category between accessible savings, planned expenses, and extra debt repayment. This general guide is not a personalized debt plan.
What is the difference between the 50/30/20 rule and zero-based budgeting?
The 50/30/20 rule sets broad percentage targets for three categories. Zero-based budgeting gives every unit of income a job until planned income minus outgoings equals zero. You can combine them by using 50/30/20 as targets and assigning specific amounts within each category.
Conclusion: What should you do first?
The 50/30/20 budget rule is a starting point: 50% for needs, 30% for wants, and 20% for savings and extra debt repayment. A useful budget covers essentials, makes trade-offs visible, and supports your goals — even when the percentages need to change.
Sources
Tags: BudgetingHow-ToStep-by-Step